
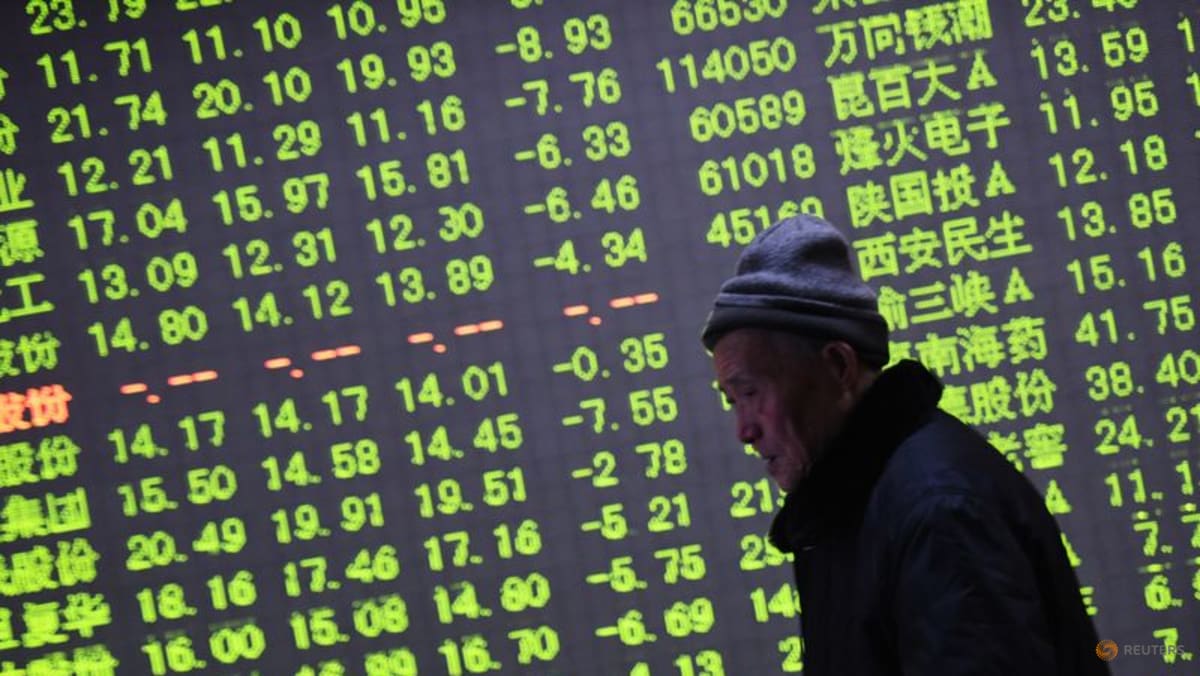
State-owned insurers have been steadily increasing their stock holdings in recent years. China Life Insurance, for instance, has scaled up artificial-intelligence-related bets and raised its equity allocation to 19.2 per cent of its portfolio by the end of June, from 16.9 per cent in 2025.
Beyond the hunt for higher returns, insurers have been responding to policymakers, who want them to provide more long-term capital to the stock market – a priority that the head of China’s securities regulator reiterated in a high-profile speech in mid-June. Talk about bad timing.
In recent days, authorities have issued window guidance to several major insurers, requiring them to report their equity holdings, refrain from cutting their losses, and align investment decisions with broader economic goals.
WHO WILL BE LEFT TO BLAME?
The government now appears to be grappling with an unintended consequence of its own policy.
Insurers may be more patient investors than hedge funds, but they still have to manage risk and meet claims and other liabilities. That limits their ability to sit indefinitely on mounting losses – and can force them to cut exposure during severe market downturns.
Insurers, in other words, cannot be as reliably countercyclical as the “national team”, whose primary purpose is market stabilisation.